Employee Christmas Parties and Gifts – Any FBT?
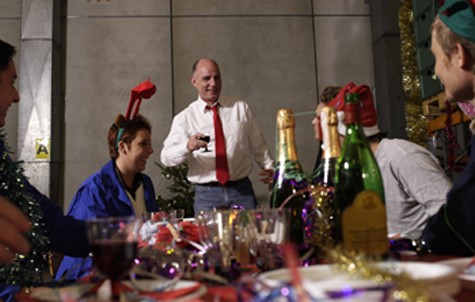
The Christmas break-up party and/or gifts to employees can be exempt from Fringe Benefits if a few rules are followed.
The cost can be exempt as either an exempt property benefit or an exempt minor benefit.
Exempt Property Benefits
- Costs like food and drinks provided for employees as part of a Christmas party, on a working day on business premises and consumed by current employees of that business.
Exempt Minor Benefits
This is applicable when the property benefits exemption doesn’t apply (i.e. because the party is held at a restaurant or separate venue).
- The cost per employee must be less than $300 (GST inclusive)
- Associates of employees such as spouses and children are regarded as employees (hence the limit for an employee and partner would be $300 each)
The minor benefits threshold of less than $300 applies to each benefit provided, not to the total value of all associated benefits.
Gifts are also considered separately from the Christmas party, so provided the cost of a gift and the party are each less than $300, then both would be exempt from FBT.
AcctWeb
.
Hot Issues
- Steps to close a business
- Paid parental leave super contributions have started
- How Do I Write Legally Compliant Terms and Conditions for My Business?
- Don’t get caught out at tax time with your multiple jobs
- Division 296 tax on large super balances
- More of the same with latest missive from Treasury
- 'No place to hide': ATO puts contractors on notice over $1bn in missing TPAR payments
- Check out the largest castles by country
- ATO no longer treating debt the same as during COVID
- Warning for early lodger this tax time!
- Global companies turn to cost-cutting amid ongoing inflation
- Don’t get caught out at tax time with your multiples jobs
- Does Your Small Business Need to Follow AML Privacy Rules?
- SMEs warned as ATO ramps up tax debt collection
- Taxpayer given 35% penalty for BAS recklessness
- How Our Diets have Changed.
- Tips to help you this tax time
- Tax Time Checklists Individuals; Company; Trust; Partnership; and Super Funds
- ATO warns millions of Australian chasing tax deductions to stop making 'unusual' claims
- Impersonation scams are on the rise
- Components of a cyber security plan
- Social Security Payments and Their Effect on Discretionary Trusts
- LRBA ban no better for housing supply or retirement, accountants clap back
- The evolution of the world's languages
- 2026 Year-End Tax Planning Guide – Part 1
- 2026 Year-End Tax Planning Guide – Part 2
- PAYDAY SUPER STARTS 1 JULY 2026 – Planning guides
- Payday Super: 6 Things Small Businesses Need to Know
- SMEs to be hit hardest by new trust tax reforms
Article archive
- April - June 2026
- January - March 2026
- October - December 2025
- July - September 2025
- April - June 2025
- January - March 2025
- October - December 2024
- July - September 2024
- April - June 2024
- January - March 2024
- October - December 2023
- July - September 2023
- April - June 2023
- January - March 2023
- October - December 2022